
ERP and Financial System Integration for Collections
ERP and Financial System Integration for Collections: Automating Without Replacing What Already Works
By Gabriel Borges Aguiar · September 21, 2026 · 6 min read
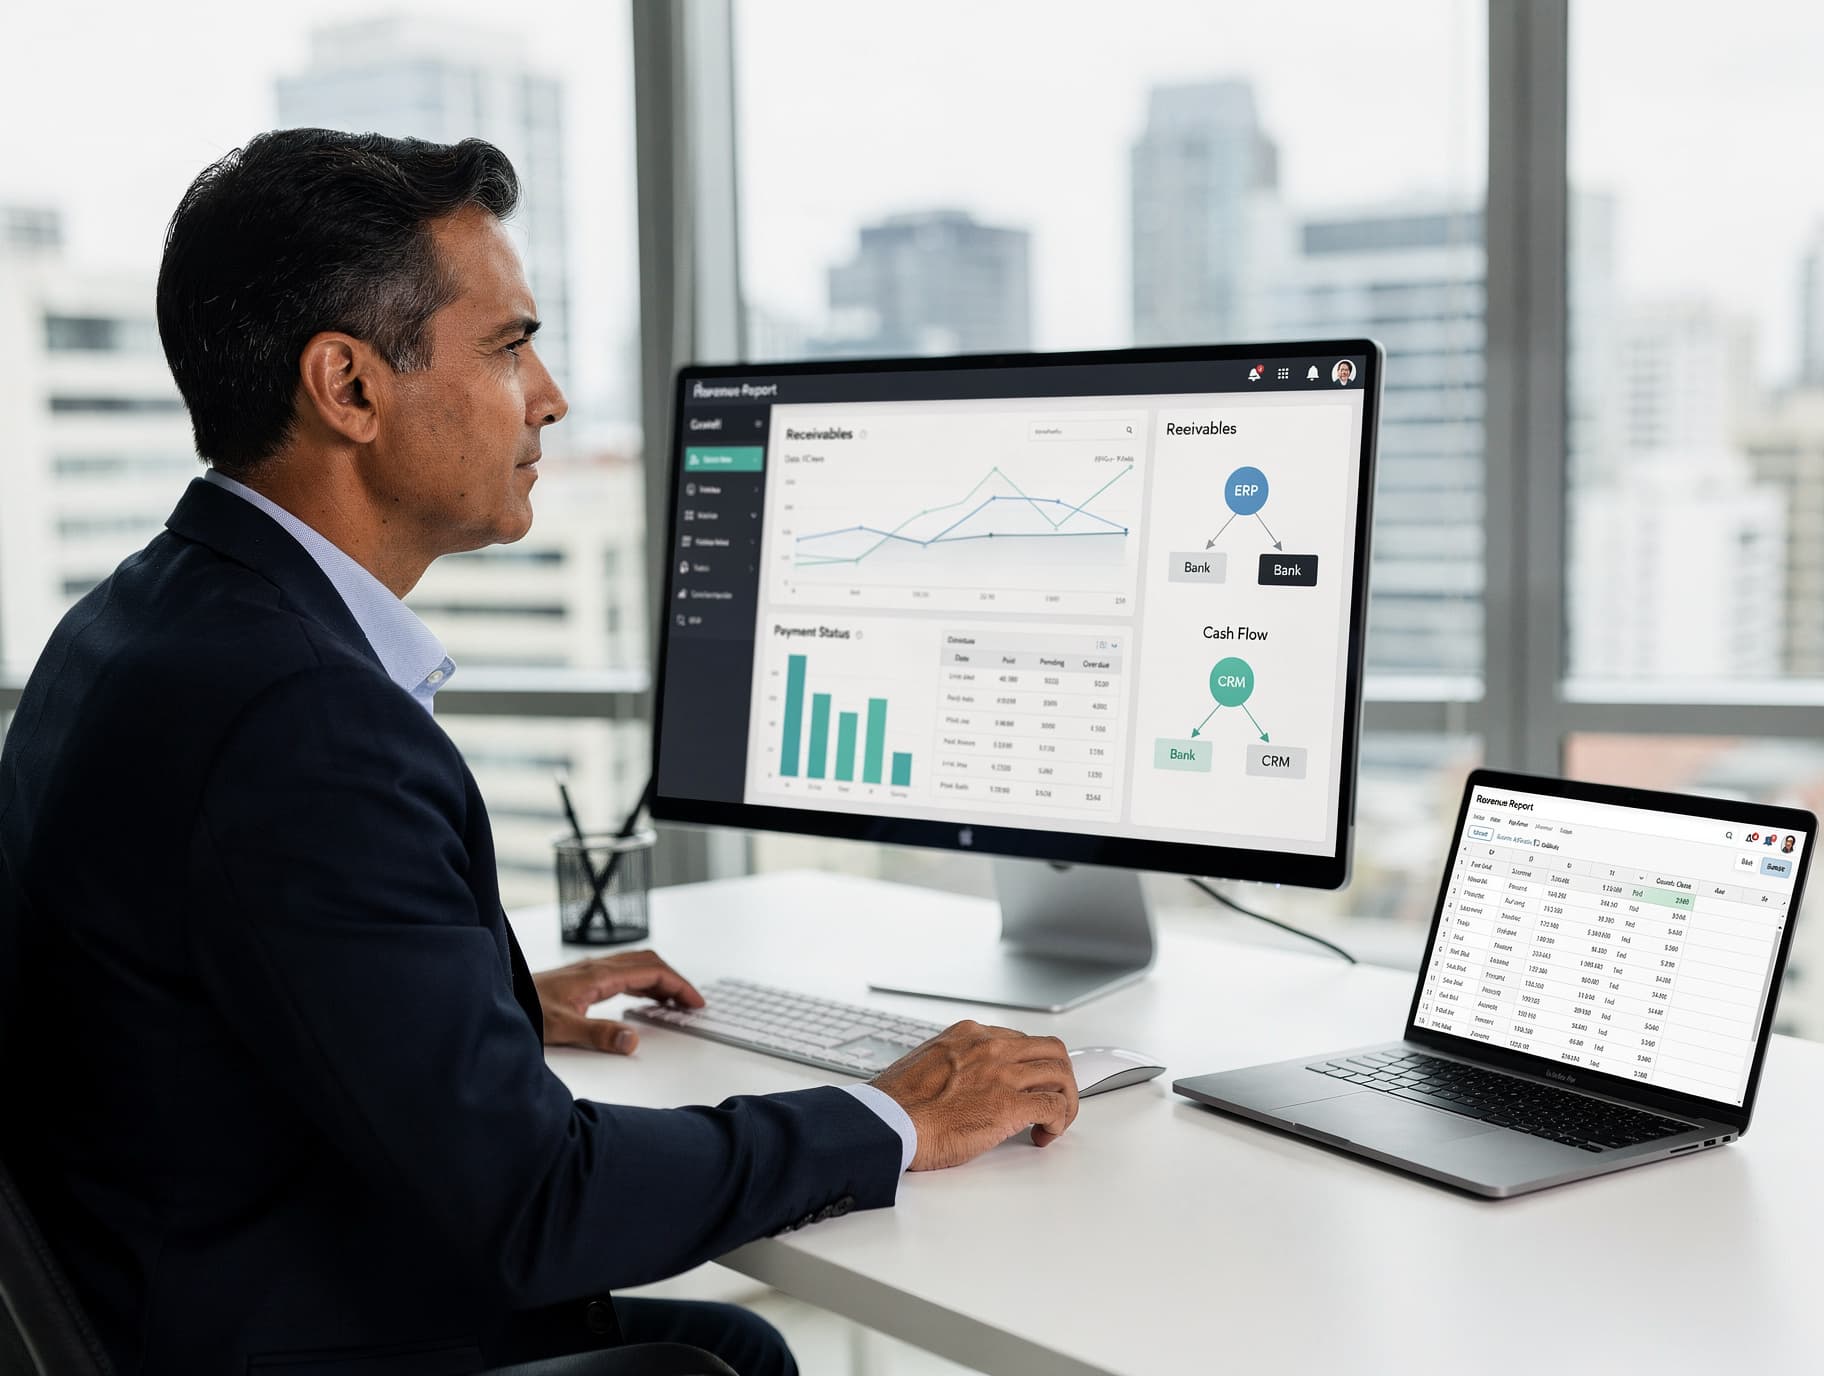
ERP and Financial System Integration for Collections: Automating Without Replacing What Already Works
For many companies, the biggest obstacle to automating collections isn't technology. It's the fear of touching the system that runs the entire finance operation. The ERP holds invoices, contracts, payment records, and reports, and any project that threatens that foundation feels expensive, slow, and risky.
The good news is that automating collections doesn't require replacing anything. Integrating with your existing system or financial ERP lets AI agents act on the data the company already has, run the collection flow, and feed the results of every action back into the system. The ERP stays the single source of truth. Automation becomes the workforce that acts on top of it.
The Cost of Running Collections Disconnected from the Financial System
When collections live outside the ERP, the routine tends to be predictable: someone exports a spreadsheet, someone else sends messages, finance checks proof of payment, and the reconciliation only reaches the system hours or days later. In that gap, a customer who already paid gets a new collection message, the team works with outdated information, and the company loses speed exactly where it matters most.
This model also has a clear scaling limit. Every new invoice adds to the manual task queue, and the usual fix is hiring more people to copy, paste, and check data. Cost grows along with the portfolio, with no guarantee of a consistent approach.
Integration fixes the problem at its source. Instead of the team carrying information from one system to another, the systems talk to each other, and collections react to financial events as soon as they happen.
What AI Debt Collection Does Once It's Integrated
Once connected to the ERP or financial system, the platform knows each customer's real position: open invoices, due dates, amounts, payment history, and past agreements. From there, more than 30 AI agents run the collection flow autonomously, 24 hours a day.
Before the due date, the platform sends personalized preventive reminders. After an account goes overdue, it applies credit recovery flows based on customer profile and negotiates in real time, with progressive discounts based on days overdue and installment agreements within company defined rules. It also resends invoices, segments the portfolio by payment behavior, and recognizes payments to reconcile them automatically.
When a company chooses to include credit bureau reporting in the process, it follows the rules configured within the operation itself. Every communication and negotiation complies with applicable collection regulations.
Two-Way Integration: Reading From and Feeding Into the System
A useful integration doesn't stop at reading a list of delinquent accounts. The real value shows up when information flows in both directions.
Going one way, the ERP feeds the platform what it needs to act with context: customer, invoices, due dates, amounts, status, and contact channels. Going the other way, the platform feeds the financial ecosystem what happened: agreements closed, payment promises, new due dates, identified payments, and reconciliations.
Without that return flow, the company is just trading one spreadsheet for another isolated screen. With it, the finance team sees the current situation without manually reconciling information, and no customer who has already paid stays in an active collection sequence.
No System Swap, No Dependence on IT
One of the factors that weighs most on this decision is the impact on the company's existing environment. The platform was designed to connect with current systems, without requiring the company to replace its ERP, rebuild processes, or maintain new internal structures.
In practice, that means three things:
Connects to what you already use. The platform integrates with financial systems, ERPs, and other operational tools, instead of proposing a migration.
Configured through the dashboard. Rules, playbooks, discounts, and limits are set directly in the admin panel. The AI runs on its own, without depending on the vendor's team for day-to-day operations.
Fast results. Implementation doesn't require long projects. Companies typically start seeing results in about 7 days.
For the manager, that changes the nature of the project. It isn't an infrastructure overhaul. It's the activation of an operational layer on top of a foundation that already exists.
AI Autonomy, With Rules Set by the Company
Integrating systems doesn't mean handing decisions to a black box. Financial leadership defines, in the dashboard, what the AI can do: which customers can receive a discount, at what percentage, how many installments an agreement can include, when a case needs to go to a person, and what limits apply to credit bureau reporting.
The AI operates within that boundary. The manager keeps control of strategy and tracks everything in real time: every action, every negotiation, and every outcome are visible in a dashboard that combines analytics, a Kanban board, and a CRM in a single platform. Autonomy with traceability is what turns automation into governance.
Four Steps to Integrate Without Disrupting Finance
1. Simple integration. Connect the platform to your ERP or financial system. The initial goal is making sure the AI sees invoices, due dates, and payment status accurately.
2. Configure your rules. Define your collection playbooks: overdue brackets, communication tone, discounts, installment options, escalation criteria, and credit bureau reporting limits. The clearer the policy, the safer the autonomy.
3. Let the AI work. With the rules active, agents run reminders, negotiations, invoice resends, and reconciliations without continuous manual oversight. Start with a specific portfolio segment to validate behavior before scaling up.
4. Track the results. Use the dashboard to monitor recovery, active conversations, success rate, and week-over-week progress. With real data, adjust the rules and expand scope to new portfolios.
What to Ask Before Choosing an AI Collections Platform
Not every platform that promises integration delivers the same result. Before deciding, it's worth confirming a few points.
Can the solution connect to the system you already use, or does it require switching tools? Is the integration two-way, feeding agreements and reconciliations back into the financial system? Can your team configure rules and playbooks on its own, without opening a support ticket for every adjustment? Is there full visibility into what the AI did, with a complete history of conversations and negotiations? Does the operation comply with collection regulations?
If the answer to these questions is yes, collections stop being a queue of manual tasks and start working as a continuous operation, connected to cash flow and to the ERP.
The final test is simple: if your invoice volume doubled tomorrow, would your operation need to double its headcount? With the right integration, the answer is no. The platform connects to your systems, runs recovery end to end, and keeps your company in command of every rule, approval, and metric.