
Collections Without a Dedicated Tool: The Cost of Improvising
Spreadsheets, an ERP, and personal WhatsApp accounts don’t add up to a collections operation. Learn why recovering payments requires a purpose-built tool.
By Gabriel Borges Aguiar · October 21, 2026 · 7 min read
Your Company Collects Payments, but Doesn’t Have a Collections Tool
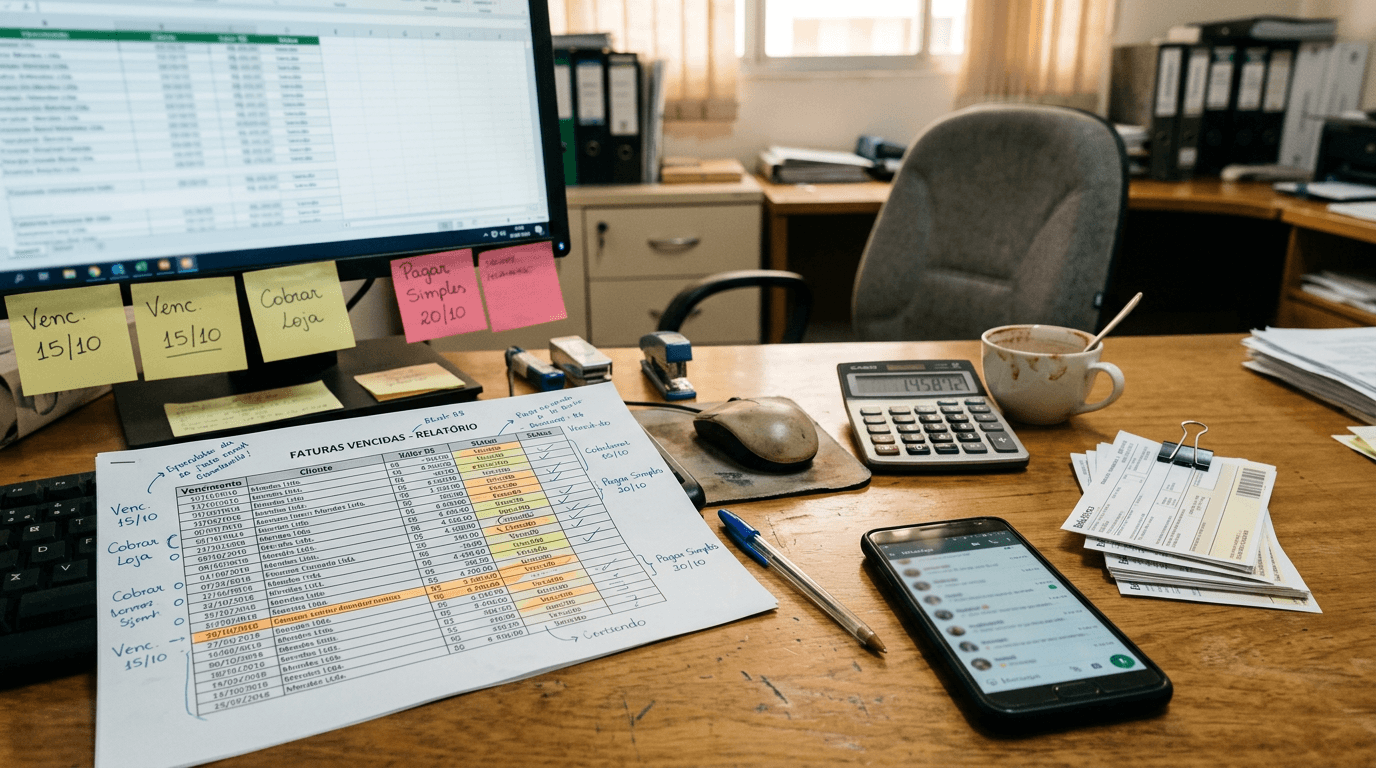
Ask a finance manager where the company’s collections operation lives, and the answer rarely points to a system. It’s partly in the ERP, partly in a shared spreadsheet, partly in the CRM the sales team uses, and most of the time in the personal WhatsApp account of whoever was assigned to “chase payments.” The company collects every day, but it doesn’t have a tool built for collections.
This setup works while the portfolio is small and the person who knows each customer stays with the company. When the volume grows, or that person takes time off, the improvisation shows up as forgotten invoices, customers contacted after they’ve paid, and payment arrangements no one knows were honored.
The question isn’t whether the company has technology. Almost all companies do. The issue is that none of the tools it uses was designed for the most sensitive task in accounts receivable: turning an overdue invoice into cash.
Collections Running on Borrowed Tools
Each system in the company has a clear owner and purpose. The ERP manages finance. The CRM organizes sales opportunities. The bank issues payment slips. WhatsApp is used to talk to customers. Because collections doesn’t have a home of its own, it ends up spread across all of them.
The ERP knows an invoice is overdue, but it doesn’t talk to the customer. The sales CRM records interactions, but it was built to move deals forward, not track payment promises. The bank sends standardized reminders without knowing whether the customer has a history of late payments or is already negotiating. And the analyst’s WhatsApp account holds the operation’s most important conversations on a device the company doesn’t control.
The result is a collection process stitched together by hand. Someone exports the overdue list, compares it with last month’s spreadsheet, checks the bank statement to see who paid, sends messages one by one, and records replies wherever they can. Every step depends on human attention to keep things from falling apart.
Why Each Tool Only Solves Part of the Problem
The problem with borrowed tools isn’t their quality. It’s that each one sees only one part of the collections cycle—and the most valuable part is right in the gaps between them.
A Spreadsheet Doesn’t Know What Happened Today
A spreadsheet is a snapshot. It shows the portfolio as it looked when it was exported, and it becomes outdated with every payment received. If a customer paid at 10 a.m. and the list was generated at 8 a.m., they’ll still get a collection message that afternoon. What’s more, spreadsheets don’t capture the tone of a conversation, the customer’s objection, or the promised payment date in a way that lets someone else pick up where things left off.
A Sales CRM Focuses on Closing, Not Recovering Payments
Adapting the sales CRM for collections may seem like a cost-effective solution, but the underlying logic is different. Sales works with stages that move deals forward. Collections works with delinquency stages, discount approval limits, installment plans, broken agreements, and payment reconciliation. Forcing this workflow into a sales pipeline means improvised fields and reports that don’t answer finance’s questions.
Personal WhatsApp Accounts Lack Oversight
A large share of negotiations happen on WhatsApp because that’s where customers respond. But when conversations are on an employee’s phone, the company has no centralized history, can’t audit what was offered, and loses context when that person changes roles. Worse, there’s no guarantee that discount limits and communication guidelines were followed.
Automated Bank Reminders Don’t Negotiate
Payment reminders help prevent missed due dates, but that’s where their usefulness ends. When a customer replies asking for a copy of the invoice, a different payment date, or alternative terms, there’s no one on the other end. The automation sends messages, but doesn’t respond. And the moment a customer shows they’re willing to pay is exactly when the operation needs to be available.
Signs Your Company Needs a Dedicated Tool
Many companies don’t realize they lack a collections tool until cash flow gets tight. But the signs usually appear earlier. See if any of these have become part of your routine:
No one can say, within a few minutes, how much is overdue by delinquency stage.
Customers complain about being contacted after they’ve already paid.
Negotiation terms vary depending on who handles the customer.
Payment promises aren’t automatically followed up on the agreed date.
Collections stop when the person in charge is unavailable.
A customer’s negotiation history is scattered across email, spreadsheets, and phones.
Someone has to check the bank statement manually to see whether an agreement was honored.
Two or three of these signs are enough to show that collections no longer fits into borrowed tools. From that point on, every new customer in the portfolio adds manual work instead of increasing recovered revenue.
What a Collections Tool Can Do That Other Tools Can’t
A dedicated tool starts with a simple premise: the collections cycle begins before the due date and ends only when payment is settled. Everything that happens in between needs to be in one place, with workflows designed specifically for the job.
That means checking the actual status of each invoice, segmenting the portfolio by delinquency stage, amount, and payment behavior, and applying a contact sequence suited to each customer profile. It also means responding when a customer writes in, sending a copy of the invoice immediately, presenting offers within the approved policy, formalizing the agreement, and tracking each installment through payment reconciliation.
With artificial intelligence, this work no longer depends on someone being available. Autonomous agents handle WhatsApp conversations 24/7, apply the company’s discount and installment rules, and escalate only cases outside the policy to the human team. Every interaction is recorded and visible to management.
That’s the Cobrança IA model: a dedicated collections platform that connects to the systems a company already uses and manages the operation from end to end, while keeping the company in control of its rules, approval limits, and metrics. The ERP remains the source of financial truth. At last, collections has a home of its own.
How to Replace Improvisation in Four Steps
Adopting a collections tool doesn’t require shutting down operations or replacing existing systems. The safest approach is to organize what’s already in place and transfer execution gradually.
Bring together what’s currently scattered. Identify where invoices, contact details, conversations, and agreements are stored. This inventory reveals how much rework is involved today and which integrations will be needed.
Turn informal know-how into rules. Much of the collections policy lives in the heads of the people who handle it. Document delinquency stages, discount limits, maximum installment counts, contact hours, and situations that require human approval.
Connect the tool to your financial source of truth. The platform needs to read the actual status of invoices in the ERP or financial system and sync back agreements, promises, and identified payments. Without this connection, the company is just replacing one spreadsheet with another isolated screen.
Start with a subset and compare results to the baseline. Activate the tool for one delinquency stage or customer segment, then track recovery rates, time to first contact, promises kept, and hours saved by the team. Once you have the numbers, expand to the rest of the portfolio.
The Metrics You Can See Only When Collections Has a Home of Its Own
One of the less-discussed benefits of a dedicated tool is visibility. When collections is spread across multiple systems, metrics have to be assembled manually at the end of the month—when it’s already too late to change course.
With the operation centralized, managers can track recovery rates by delinquency stage, amounts recovered by channel, average time to an agreement, the rate of promises kept, and operating cost per dollar recovered in real time. They can also see which offers convert best and which ones are more likely to result in a broken agreement.
These data change the conversation inside the company. Collections is no longer discussed in terms of effort (“we’re calling everyone”) and instead becomes a conversation about results (“we recovered this amount in this stage, at this cost, within this timeframe”).
Every company that sells on credit has a collections operation, whether it wants one or not. The difference is whether it runs on improvisation, spread across systems that weren’t designed for the job, or with a dedicated tool that tracks every invoice from its due date through payment. The first option seems cheaper—until the day cash flow reveals what it really cost.